Ola Electric Shares Decline 6% After Company Reports ₹336 Cr Loss In Q1
Ola Electric Mobility shares declined more than 6% in early trading on Monday after the electric vehicle maker announced its June-quarter results. The stock fell 6.06% to ₹38.58 apiece on the BSE before recovering partially. The company reported a consolidated net loss of ₹336 crore for Q1FY27, compared with a loss of ₹428 crore in the same quarter last year and ₹500 crore in the March quarter.…
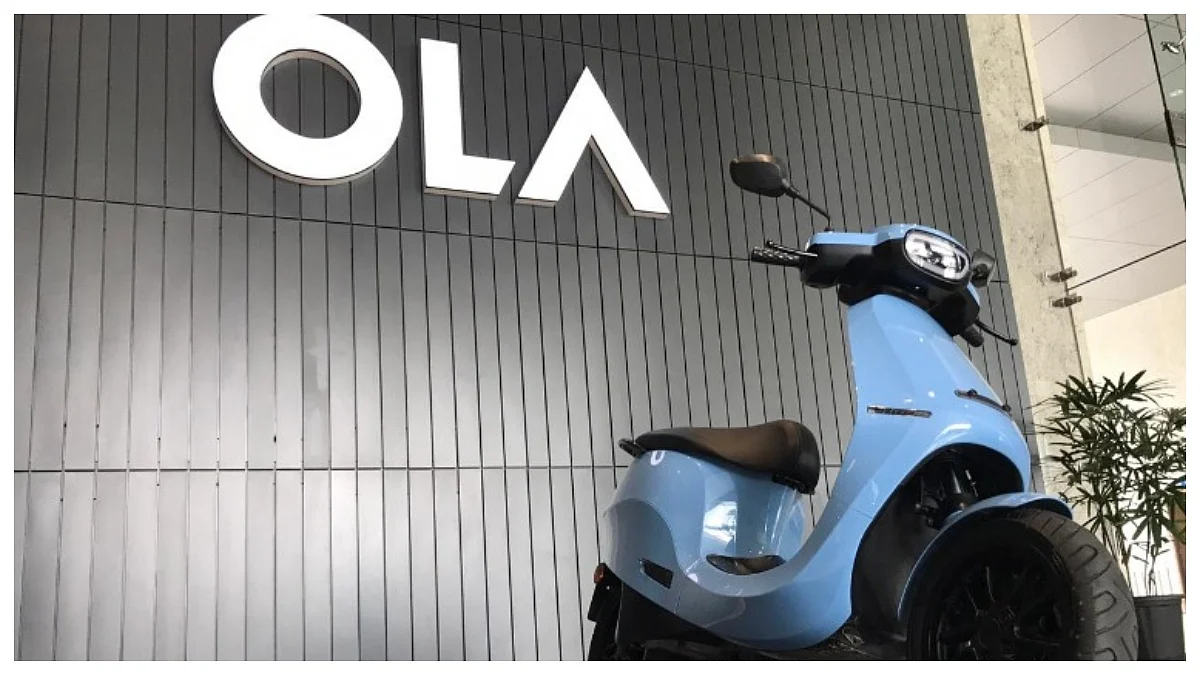
Ola Electric Mobility's shares fell more than 6% in early trading on Monday following the release of its Q1FY27 results. The electric vehicle company reported a ₹336 crore net loss for the quarter, a decrease from last year's loss of ₹428 crore. Revenue from operations also fell by 45%, reaching ₹455 crore compared to ₹828 crore in the previous year.
Despite the revenue decline, Ola Electric saw a significant increase in vehicle registrations, with a 97% quarter-on-quarter rise. This performance surpassed the growth rate of the entire electric two-wheeler market, which expanded by 17% during the same period. The company's market share in Q1FY27 rose to 8.4%, up from 5.1% in the prior quarter. Revenue from auto sales also increased by 72% sequentially.
Orders nearly doubled, with 44,000 units on the books, and deliveries rose to approximately 39,200 units from 20,256 units in Q4FY26. However, analysts expressed caution, citing weak sales volumes, lower average selling prices, and pressure on margins. Some brokers noted that cost-control measures and the reversal of a provision linked to battery production-linked incentive (PLI) targets offered some relief, but operational challenges persisted.
Brokerage firms maintained a cautious outlook on Ola Electric. Citi retained its Sell rating with a target price of ₹26, emphasizing that weaker volumes and lower gross margins outweighed the benefits of cost reductions and the PLI provision reversal. Goldman Sachs upgraded its rating to Neutral while raising the target price to ₹40, citing ongoing cash burn and operational weaknesses.
Kotak Institutional Equities also kept its Sell recommendation with a target price of ₹20, highlighting improving volume scale as a major challenge and warning that persistent cash outflows may necessitate additional capital if sales momentum does not improve.
Written by urgent.news from Free Press Journal's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.