Broker’s Call: TVS Motor (Buy)
Geojit Financial
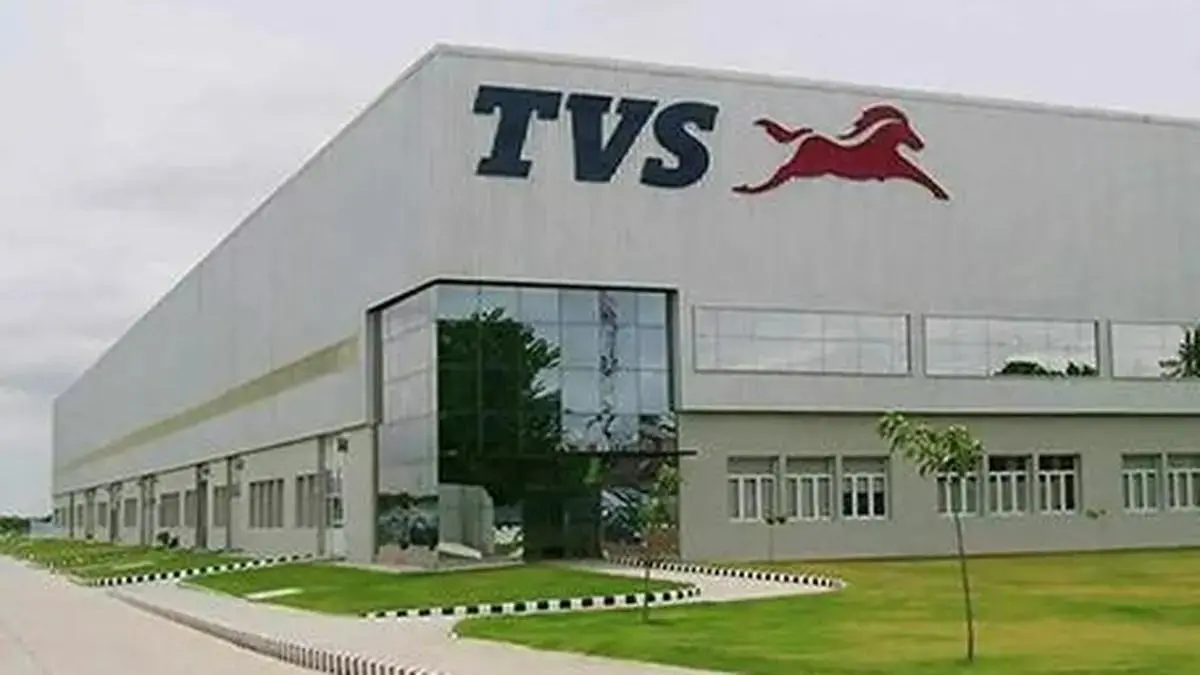
TVS Motor, a leading two-wheeler manufacturer in India, reported a strong performance in Q1FY27. Revenue surged 38% year-over-year to ₹13,896 crore, driven by a 28% increase in vehicle volumes. EBITDA expanded 41% to ₹1,779 crore and profit after tax (PAT) increased 51% to ₹1,174 crore, including a significant ₹150 crore gain from fair valuation.
Gross margin decreased slightly to 27.2%, amidst rising commodity inflation and a shift in product mix. However, EBITDA margin improved 28 bps to 12.8%, thanks to operating leverage and cost optimisation. Electric vehicle (EV) sales jumped 86% to 1.30 lakh units, with revenue of ₹1,780 crore. Export sales reached a record 4.68 lakh units, up 33%, contributing ₹3,634 crore to international business revenue.
Three-wheeler sales grew 48% to 66,697 units. Despite healthy demand outlook backed by GST rationalisation, income-tax relief, and improving affordability, factors like monsoon progress and inflation require monitoring. Management anticipates Q2 momentum to match or exceed Q1 across domestic and export markets. The financial advisory suggests a target price of ₹4,780 for TVS' standalone business, valuing it at 37 times FY28 earnings per share (₹4,525).
TVS Credit Services, valued at 2 times price-to-book ratio (15% holding discount), complements the outlook.
Written by urgent.news from Hindu BusinessLine's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.